



Buying insurance online makes comparing options and completing the purchase from your couch pretty painless. But what happens once you spot a mistake after paying, realize you actually need more coverage than you bought, or your situation changes?
Here’s the good news: some changes are genuinely possible after purchase. What you can actually change comes down to the type of insurance, the insurer’s own rules, and the terms sitting in your specific policy.
Some updates, like fixing a spelling mistake, are usually simple enough. Others — increasing coverage, swapping out an insured vehicle — might need approval, an extra payment, or even a completely new policy.
If something needs fixing, contact your insurer as soon as you can. Here’s what to know about updating insurance you bought online.
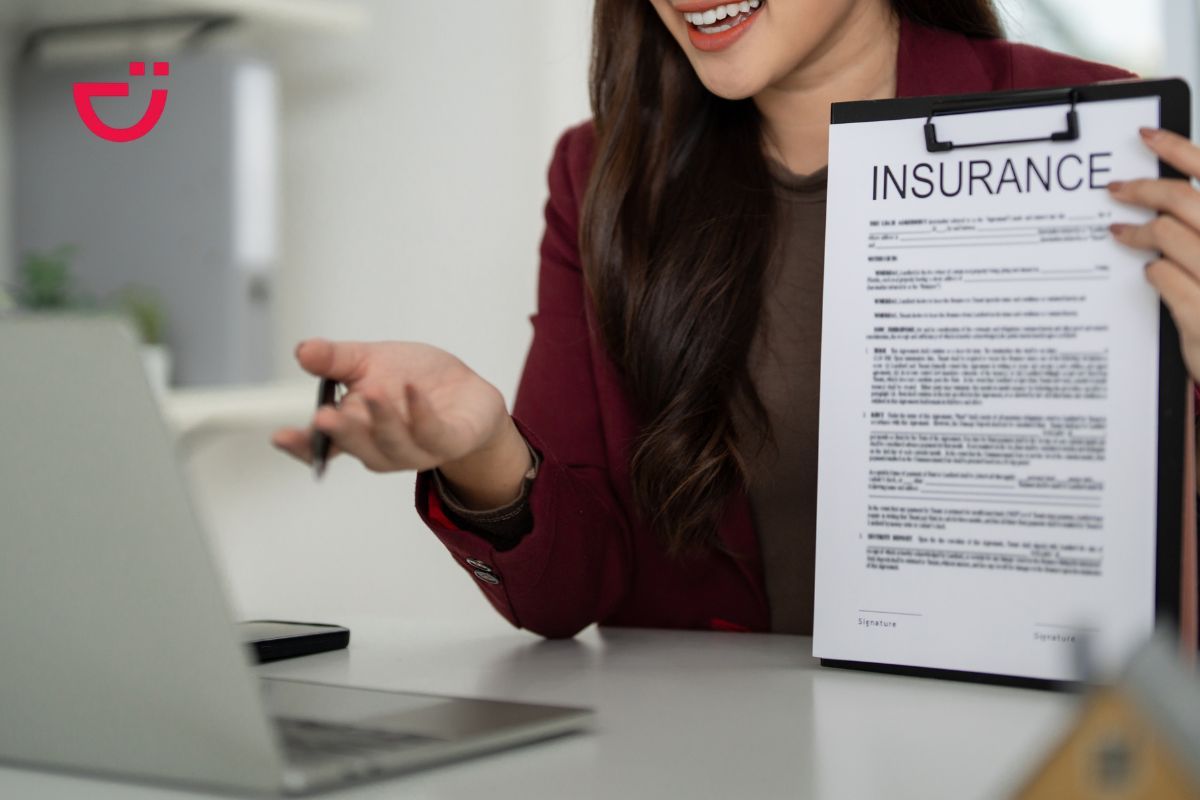
Can You Change an Insurance Policy After Buying It Online?
Yes, you may be able to change certain details after purchase — but not every request gets a yes.
Every policy has its own terms governing when and how changes happen, and that process shifts depending on what type of insurance you actually bought.
Some changes can be made directly to the existing policy. Others mean cancelling it and buying a new one entirely. And there may be conditions around exactly when a change actually takes effect, not just whether it’s allowed.
It’s also worth separating two different things: correcting an error versus requesting something new. If your policy doesn’t match what you originally selected, explain the discrepancy clearly and include your purchase confirmation if it helps your case.
What Changes Can You Request?
What’s actually available depends entirely on your specific policy, but a handful of situations come up constantly.
Correcting Personal Information
This is probably the single most common reason people reach out for an update.
Maybe there’s a spelling mistake in your name, a wrong ID number, or outdated contact details. These feel minor, but accurate information genuinely matters when you’re managing a policy or submitting a claim later.
Contact your insurer and explain exactly which detail needs fixing. You might need to provide ID or supporting documents to confirm the correct information.
If you catch the error shortly after buying online, keep your purchase confirmation—it can help show what you submitted in the first place.
Don’t assume the insurer will catch and correct an error on their own, or that an incorrect detail won’t affect a claim down the line. Ask for confirmation once it’s fixed, and keep a copy of the corrected policy if a new document gets issued.
Updating Coverage or Benefits
Sometimes the issue isn’t your details at all — it’s what’s actually included in the policy.
After going through your health insurance documents, you might realize the outpatient benefits genuinely don’t cover what you need. Or you might want to add an optional benefit to a different type of policy entirely.
Whether that’s possible comes down to the insurer and the policy terms. Some policies allow certain changes mid-coverage; others require buying a different plan outright.
Increasing coverage or adding benefits can also bump up your premium. The insurer may need to review the request before confirming anything’s actually changed.
Before you go ahead, ask directly:
- Is this benefit even available under my current policy?
- Will I need to pay an additional premium?
- Are there new conditions, exclusions, or waiting periods attached?
- When does the updated coverage actually kick in?
Make sure you genuinely understand the answers before agreeing to anything. Don’t assume the extra coverage is active just because you asked for it, or because you’ve already paid for it.
Changing Policy Dates or Other Details
Sometimes it’s the policy period itself that’s the problem, not the coverage.
Maybe the start date doesn’t match when you actually need coverage, or some other detail needs fixing. In these cases, contact the insurer and flag the issue the moment you spot it.
If the date’s wrong because of a processing error on their end, the insurer should walk you through how to get it corrected. If you want the dates changed because your own plans shifted, different conditions might apply.
Say you bought travel insurance for a trip, and then your travel dates change — ask whether the policy dates can move too. What’s genuinely available here depends on the policy terms, and whether the requested change is even permitted in the first place.
Worth keeping in mind: changes usually can’t be applied retroactively. The insurer typically can’t offer coverage for a period that’s already passed, or for something that happened before the change was actually approved.
Always get revised dates confirmed in writing, and check exactly when the new terms actually take effect.
Changing Vehicle or Other Insured Details
Some changes involve the actual thing or person being insured, not your personal information at all.
If you’ve got motor insurance and you replace your vehicle, you’ll need to contact the insurer to find out how to handle that. Don’t assume the existing policy automatically rolls over to cover the new car.
Same logic for property insurance — if something about the insured property changes, the insurer may need to reassess the whole policy.
Depending on the situation, they might allow a straightforward update, adjust the premium, or require an entirely new policy.
Give them accurate details about whatever’s changed, and ask directly whether your existing coverage stays valid while the request is actually under review. This matters a lot, especially when the change touches what’s actually being insured.
When Can You Make Changes?
Generally, the best move is contacting your insurer the moment you realize something needs changing. Acting early gives you more room to understand your options and gather whatever documents are needed.
Some policies allow changes mid-coverage; others restrict when certain updates can happen at all. The type of change matters too — correcting a personal detail typically follows a very different process than increasing coverage or swapping out an insured item.
It’s also worth checking whether a cancellation or cooling-off period applies to your purchase. Depending on the policy and its terms, this might give you a window to cancel outright. That said, it’s not guaranteed across every policy or type of insurance — don’t assume it applies to yours.
If you’ve just bought insurance online and realize you picked the wrong option entirely, contact the insurer or platform right away. Ask whether the policy can simply be corrected, or whether you’d need to cancel and repurchase.
Don’t wait until you actually need to make a claim before dealing with an error. And remember — requesting a change isn’t the same as having it approved. Until you get confirmation, you’re still bound by the existing policy’s terms, so don’t assume new coverage is active just because you asked.
Will Changing Your Policy Cost Extra?
It really depends on the type of change.
Correcting a spelling mistake or updating contact information might not touch your premium at all — though the insurer’s own process will ultimately decide whether any charge applies.
Changes that increase the insurer’s risk, or add new benefits, can mean a higher premium though. Adding coverage, or swapping an insured vehicle, could genuinely affect the price.
If you end up cancelling and buying a different policy instead, factor in cancellation fees, refund conditions, and whatever the new premium looks like.
Before confirming any change, ask the insurer to spell out the actual financial impact. Find out whether you’ll pay extra, whether a refund applies anywhere, and whether the change touches other conditions in the policy.
What to Do If You Need to Change Your Policy
If you need to update insurance you bought online, a few steps make the whole thing smoother.
- Review your policy documents. Pin down exactly what detail or benefit needs changing, and check whether the policy explains how to actually request updates.
- Contact the right support team. Reach out to the insurer, or the platform you bought through. Explain the situation plainly and ask what’s genuinely possible.
- Prepare supporting documents. Depending on the change, that might mean ID, proof of payment, your purchase confirmation, or documents related to whatever’s insured.
- Confirm the cost and effective date. Ask whether this involves an extra payment, fees, or new conditions, and confirm exactly when the change actually kicks in.
- Keep written confirmation. Save the insurer’s response and any updated documents, and check the final version genuinely reflects what was agreed.
These steps keep your records straight and cut down on confusion about your coverage down the line.
Conclusion
You may well be able to change your insurance policy after buying it online — but what’s actually possible depends on the insurer, the type of insurance, and the terms of your specific policy.
Correcting personal details is usually straightforward. Changing coverage, policy dates, or insured items often needs approval, or sometimes a whole new policy. And some changes do affect your premium.
If you need an update, contact your insurer promptly, ask about costs and conditions upfront, and keep written confirmation of whatever actually gets changed.
When comparing insurance options through Tameen.om, review the available benefits carefully so you can choose coverage that genuinely fits what you actually need.
Frequently Asked Questions
Can I change my insurance coverage immediately after buying it online?
Possibly. Some changes are available right after purchase, while others need approval or a new policy entirely. Contact your insurer as soon as you can to confirm what’s actually possible, and when any approved change would take effect.
Can I cancel my insurance policy if the details are wrong?
Cancellation might be an option, but it depends on the policy terms and whatever conditions apply. Contact the insurer first to find out whether the details can simply be corrected, or whether cancelling is genuinely necessary. Ask about fees or refund eligibility before you go ahead.
Will changing my insurance policy affect my premium?
It might. Correcting a personal detail often leaves the price untouched, while increasing coverage, adding benefits, or changing an insured item could affect the premium. Ask your insurer to confirm any additional costs before you approve the change.
Explore All Insurance Options on Tameen
Discover a wide range of insurance plans and compare coverage to find the option that best fits your needs.
 Whatsapp