



Buying insurance isn't something you should only think about the day you first purchase a policy. Your needs shift from one year to the next, and your insurance really should keep pace with those changes rather than sitting frozen.
Maybe you bought a new car, moved somewhere new, picked up some valuable belongings, or your family situation changed entirely. Even if nothing major happened on your end, the policy itself may have quietly changed at renewal without you noticing.
That's really why an annual insurance review is a genuinely useful habit. It gives you a chance to check what you're actually covered for, whether your limits still make sense, and whether you're paying for protection you don't even need anymore.
Here's a simple checklist to help you review your insurance before the next renewal comes around.
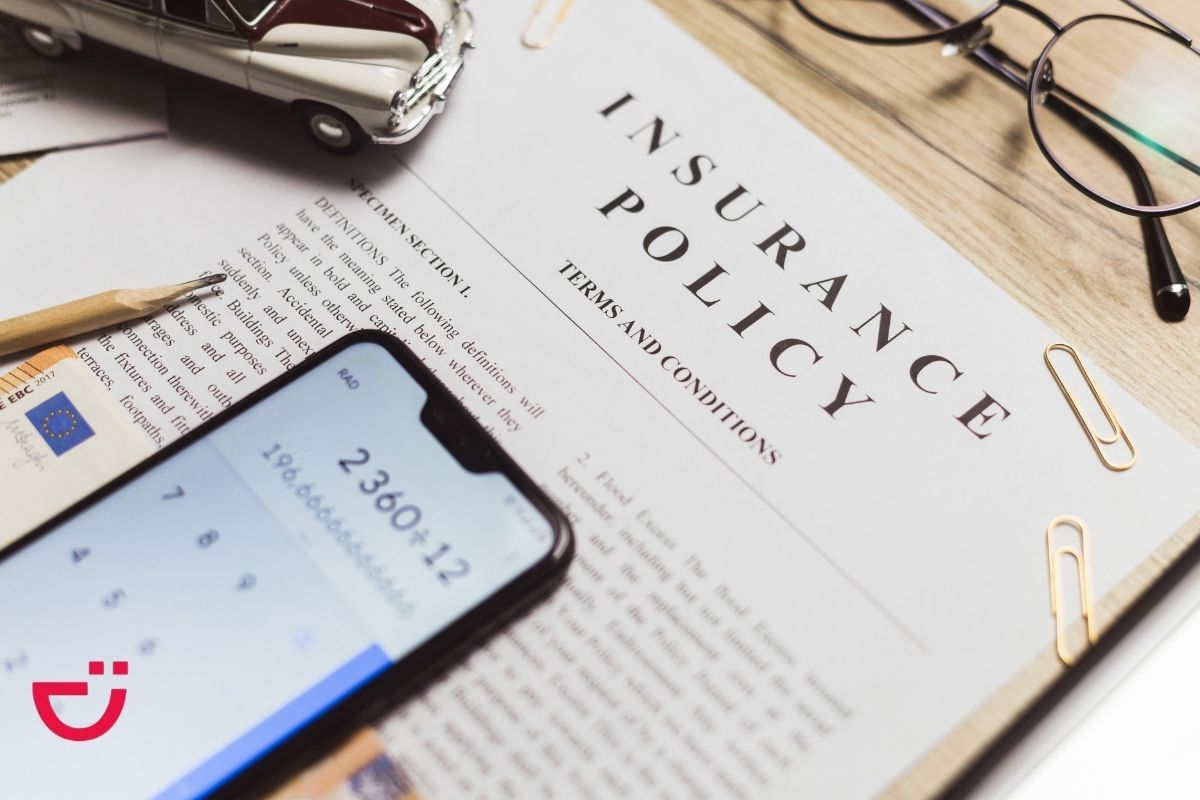
Why Should You Review Your Insurance Policy Every Year?
Insurance needs aren't identical year after year. A policy that worked well last year might not provide the right level of protection this year.
An annual review can help you:
- Check that your coverage still matches your needs
- Make sure your coverage limits are actually suitable
- Identify changes to exclusions or policy conditions
- Update incorrect personal or asset information
- Add newly purchased assets where necessary
- Remove coverage you no longer actually need
- Find gaps or overlapping coverage
- Compare your renewal price against other available options
You don't necessarily need to change your policy every single year. The point of a review is just making sure you actually understand what you have, and whether it still genuinely works for you.
When Is the Best Time to Review Your Policy?
The weeks before your policy renewal are a good window for reviewing your insurance. That gives you enough time to ask questions, make changes, or compare other options before your current policy actually expires.
You don't have to wait until renewal, though. Worth reviewing your insurance after any major changes in your life or finances too.
Worth reviewing your coverage, for instance, if you've:
- Bought or sold a vehicle
- Moved to a new home
- Purchased valuable belongings
- Got married or had children
- Taken on a new loan or financial commitment
- Changed your travel habits
- Started a business or changed your business activities
These kinds of changes can genuinely affect the type or amount of insurance you actually need.
Your Annual Insurance Policy Review Checklist
Check What Your Policy Covers
Start by reviewing the main coverage included in your policy. Don't assume your current policy's exactly the same as what you had last year.
Check whether the risks and expenses that actually matter to you are still covered. Depending on the type of insurance, that might include vehicle damage, third-party liability, medical treatment, property damage, travel emergencies, or other benefits.
Also worth checking whether any benefits have been added, removed, or changed since your last policy — insurers do update these quietly at times.
Remember coverage's always subject to the policy's terms, conditions, and exclusions, regardless of what's advertised.
Review Your Coverage Limits
Next, look at your policy limits. A policy may cover a particular risk, but only pay up to a certain amount.
Check the overall limit as well as limits for individual benefits. Some apply per claim, per person, per incident, or across the entire policy period.
Ask yourself whether these limits are still actually appropriate for your situation now, not a year ago.
If you own more valuable property than you did last year, for instance, your previous coverage limit might not be enough anymore. Similarly, changes in your vehicle, travel plans, or healthcare needs can shift how much protection you actually want.
Read the Exclusions Again
Exclusions explain what your policy doesn't cover. They matter just as much as whatever benefits are included, if not more.
Take some time to review the exclusions and check whether anything's changed since your previous policy.
Understanding exclusions helps you avoid a genuinely unpleasant surprise right when you actually need to make a claim.
If there's an exclusion you don't understand, check the policy wording or ask your insurer for clarification before renewing, not after.
Check Your Deductible and Out-of-Pocket Costs
Your deductible, sometimes called an excess, is another important part of the policy worth revisiting.
Check how much you'd need to pay yourself if you made a claim. If your policy includes co-payments or other out-of-pocket expenses, review those too.
A lower premium can sometimes come with higher costs the moment you actually make a claim. Make sure you understand these costs and are genuinely comfortable with them, not just tolerating them.
The right balance really depends on your budget and how much financial risk you're actually prepared to take on.
Review Your Personal Information
Make sure the information on your policy is accurate and genuinely up to date.
Depending on the type of insurance, this may include:
- Your name and contact details
- Your address
- Vehicle information
- Property details
- Information about insured individuals
- Other details relevant to your coverage
If something's changed, check whether you need to notify your insurer or update the policy directly.
Keeping your information accurate helps avoid problems down the line if you ever need to make a claim.
Check Your Insured Assets and Their Current Value
Take a look at the assets listed on your policy and consider whether their value has actually changed.
You may have, for instance:
- Bought a new vehicle
- Purchased expensive electronics
- Added jewellery or other valuables
- Bought new furniture or household items
- Sold an asset that's no longer yours
Make sure important new assets are covered where appropriate, and check whether anything you no longer own should actually be removed from the policy.
For property insurance especially, it's worth considering whether the value of your belongings has shifted significantly since you last checked.
Check Your Policy Beneficiaries Where Applicable
For policies where beneficiaries matter, like life insurance, review the names and details listed carefully.
Major family or personal changes may mean your beneficiary information genuinely needs updating.
Make sure it reflects your current wishes and circumstances, not something you set years ago and forgot about.
Review Your Claims History
Look back at claims you made during the previous policy period.
Think through whether those claims actually highlighted any gaps in your current protection. You might have discovered, for instance, that a particular benefit had a lower limit than expected, or that certain expenses simply weren't covered.
Keeping your previous claim documents and settlement information around also makes it easier to understand your insurance history when reviewing the next policy.
Check for Changes in Your Needs
An annual review's a good opportunity to actually ask whether your lifestyle's changed.
Worth considering:
- Do I drive more or less than I did last year?
- Have I bought a different vehicle?
- Have I moved or changed my home?
- Have I purchased expensive belongings?
- Has my family situation changed?
- Have my travel habits changed?
- Do I need additional protection I didn't need before?
Your answers here genuinely help you decide whether your existing coverage still makes sense as-is.
Look for Gaps and Overlapping Coverage
Reviewing your insurance isn't only about checking what you already have. It's also a chance to spot protection you might actually be missing.
You might discover, for instance, that an important asset isn't insured at all, or that your current limits are too low for what you actually need now.
At the same time, check for overlapping coverage. You may be paying for similar protection under more than one policy without ever realizing it.
The goal's having appropriate protection without paying for coverage you don't actually need duplicated.
Review Your Policy Documents
Keep your current policy schedule and policy wording somewhere genuinely easy to access.
When your policy comes up for renewal, compare the new documents against the previous version. Look for changes to coverage, limits, exclusions, premiums, deductibles, terms and conditions, and additional benefits.
Also review any endorsements, amendments, certificates, or other documents connected to your policy.
If something's changed and you're not sure why, ask for clarification before renewing rather than just assuming it's fine.
Should You Change Your Insurance Policy Every Year?
Not necessarily.
An annual review doesn't mean you need to switch insurers or change coverage every single year. If your current policy still meets your needs and offers suitable protection, renewing it may genuinely be the right call.
That said, if your circumstances have changed, or you find another policy that better matches what you actually need now, it's worth considering the alternatives seriously.
The goal isn't making changes for the sake of making changes. It's making sure your insurance keeps providing the protection you need, at a price that actually works for you.
Questions to Ask Before Renewing
Before you renew, run through this quick checklist:
- Does my current coverage still meet my needs?
- Are my coverage limits sufficient?
- Have any exclusions or conditions changed?
- Is my deductible still suitable?
- Is all my personal information correct?
- Are my important assets covered?
- Are my beneficiaries up to date where applicable?
- Has my premium changed?
- Have my insurance needs changed?
- Can I find another policy with more suitable coverage or better value?
If you can answer these confidently, you'll have a much clearer sense of whether your current policy's actually still right for you.
Conclusion
An annual insurance review doesn't have to be complicated. A few simple checks can help make sure your coverage still matches your needs, and that your policy information's actually accurate.
Review your coverage, limits, exclusions, deductibles, personal details, insured assets, and premium before renewal. Also think through whether anything in your life's changed that could affect the protection you actually need now.
Making this review part of your yearly routine helps you avoid gaps in coverage and make more informed insurance decisions overall. When it's time to compare your options, Tameen.om can help you review available policies and find coverage that suits your current needs.
Frequently Asked Questions
How often should I review my insurance policy?
At least once a year, ideally before renewal. It's also worth reviewing your insurance after major changes to your family, finances, assets, vehicle, home, or lifestyle in general.
What should I check when reviewing my insurance policy?
Check your coverage, policy limits, exclusions, deductibles, personal information, insured assets, beneficiaries where applicable, claims history, and renewal premium.
Should I switch insurance providers every year?
Not necessarily. The goal's having suitable coverage at a reasonable cost. Compare your current policy against other available options and consider switching only if another policy genuinely meets your needs better.
Explore All Insurance Options on Tameen
Discover a wide range of insurance plans and compare coverage to find the option that best fits your needs.
 Whatsapp