



When you’re shopping for health insurance, it’s easy to fixate on the premium and just assume everything else will sort itself out somehow. But what kind of care a policy actually covers matters just as much as what it costs. And two terms you’ll run into constantly are inpatient and outpatient care.
Both help with healthcare costs, but they apply in very different situations. Inpatient generally means getting admitted to a hospital. Outpatient covers everything that doesn’t require you to stay overnight at all.
Once that distinction clicks, comparing policies gets a lot easier, and you’re far more likely to land on coverage that actually matches how you use healthcare in real life. Here’s what each one involves, and how to check what your own policy actually includes.
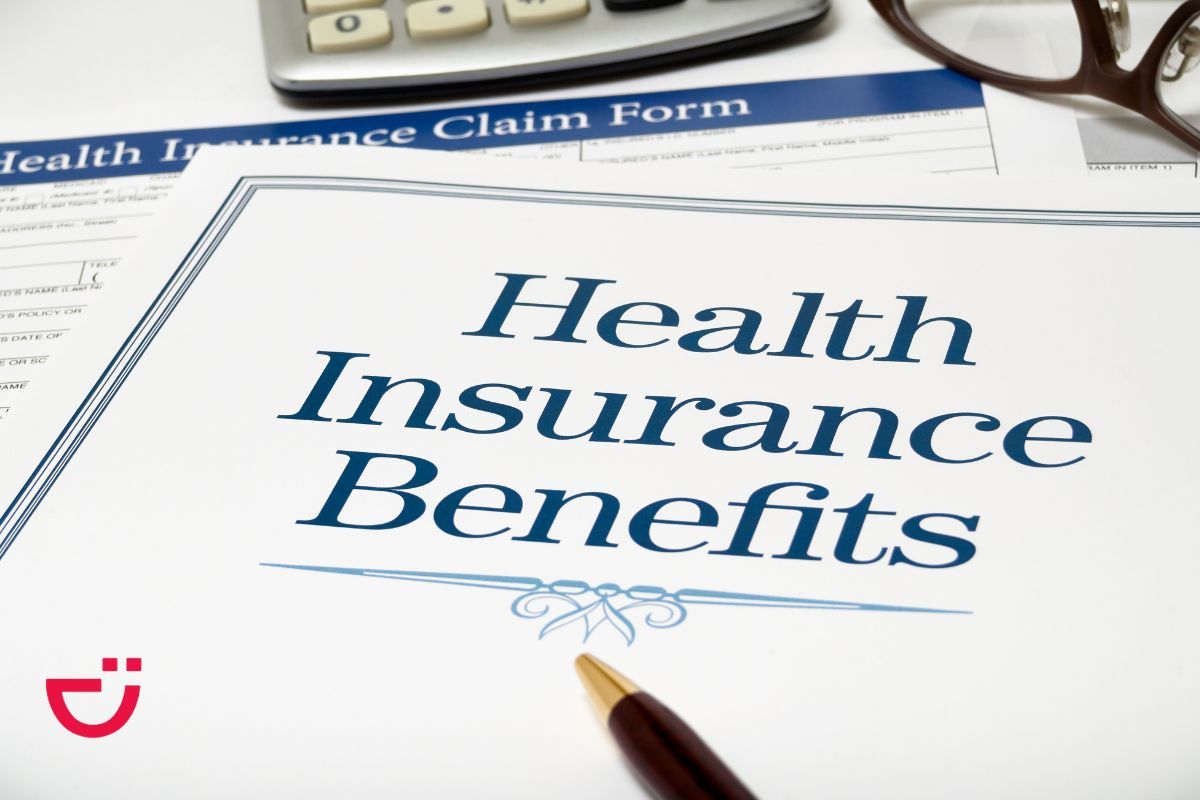
What Is Inpatient Health Insurance?
Inpatient health insurance covers eligible expenses tied to a hospital admission — staying in the hospital for treatment, whether that’s one night or two weeks. The exact line still comes down to your insurer and the specific terms of your policy, though.
Say your doctor recommends surgery that requires an overnight stay. The eligible costs there would typically fall under the inpatient section of your policy.
Inpatient coverage can include:
- Hospital room charges — the cost of the room during admission, subject to your policy’s limits
- Surgical procedures — eligible operations and related services requiring admission
- Nursing care — medical attention from hospital staff during the stay
- Medication and treatment — prescribed medicines and treatments tied to the admission, where covered
- Diagnostic tests — bloodwork, scans, whatever’s required as part of inpatient treatment
- Intensive care — eligible ICU treatment when medically necessary
This coverage matters most when treatment comes with a serious price tag attached. A hospital stay almost always brings expenses beyond just the main procedure, so it’s worth checking exactly which related services your policy actually picks up.
Worth remembering: not every admission or treatment is covered automatically. Your policy might have annual limits, exclusions, cost-sharing rules, or pre-approval requirements — and depending on how a procedure’s actually delivered, it could fall under a different benefit category than you’d expect.
What Is Outpatient Health Insurance?
Outpatient health insurance covers eligible medical services that don’t require a hospital admission — basically the visits and treatments you walk in and out of the same day.
See a doctor about a persistent cough, get a prescription, head home that afternoon — that consultation almost certainly falls under outpatient coverage.
Depending on the policy, outpatient benefits may include:
- Doctor consultations — visits to GPs and other eligible providers
- Routine checkups — appointments and preventive services your plan includes
- Diagnostic tests — bloodwork, X-rays, and other tests that don’t require admission
- Prescription medication — eligible medicines a doctor’s prescribed
- Specialist visits — dermatologists, cardiologists, whoever, subject to referral rules where they apply
- Follow-up appointments — checking on recovery or managing an ongoing condition
Outpatient coverage tends to earn its keep in everyday healthcare — it takes part of the cost of routine visits and tests off your plate instead of leaving you to cover it entirely out of pocket.
That said, outpatient benefits almost always come with their own limits and conditions attached. Your policy might cap what it pays toward consultations, prescriptions, or diagnostic tests, and you may also need a copayment or be required to stick to providers inside the insurer’s network.
If you see a doctor regularly, or you’re on ongoing medication, it’s genuinely worth checking these details closely — they’re what actually shape how much you end up paying over a full year.
Key Differences Between Inpatient and Outpatient Coverage
The core difference is whether treatment involves hospital admission, but a few other things matter once you’re actually comparing the two.
- Type of treatment. Inpatient covers admission-based care — surgeries, extended medical treatment. Outpatient covers consultations, tests, and treatments that don’t require you to stay.
- Length of stay. Inpatient means you’re admitted, possibly overnight or longer. Outpatient wraps up in a single visit, and you’re home the same day.
- Types of expenses. Inpatient expenses run to room charges, surgery, nursing care, and treatment during the stay. Outpatient expenses are usually consultation fees, diagnostic tests, prescriptions, and follow-ups.
- Coverage limits and costs. Both sides come with their own limits, deductibles, copayments, and conditions — and they’re rarely the same number. A policy might cover hospital treatment up to one annual limit while setting a completely different cap on outpatient consultations or medication. These amounts vary a lot between policies, so it’s genuinely worth reading the benefit schedule directly rather than assuming every service is treated the same.
- Approval requirements. Some inpatient treatments need pre-approval before admission or before the procedure itself. Certain outpatient services — specialist visits, scans, specific treatments — can need authorization too.
Always check requirements ahead of planned treatment. In an emergency, get care first, and sort out notification and paperwork with your insurer as soon as it’s reasonably possible afterward.
Does Health Insurance Cover Both Inpatient and Outpatient Care?
A lot of policies offer both, but how much coverage you actually get on each side varies quite a bit.
Some plans bundle hospital treatment and routine medical services into one package. Others lean heavily into solid inpatient coverage while leaving outpatient benefits fairly thin, or require you to add outpatient coverage on separately depending on the product.
That distinction matters more than people realize. Having health insurance at all doesn’t automatically mean every type of expense is covered.
Picture a policy that handles hospital admissions well but offers weak outpatient benefits. Need surgery? Eligible hospital costs are likely covered under the terms. But routine consultations, medication, or follow-up tests might carry a separate — and much smaller — limit, or might not be included at all.
Before choosing a policy, worth checking:
- Inpatient benefits — admission limits, room types, surgical coverage, related treatment costs
- Outpatient benefits — consultation limits, diagnostic tests, medication, specialist visits
- Cost-sharing — whether you’ll pay a deductible, copayment, or percentage of the bill
- Healthcare network — which hospitals, clinics, and pharmacies actually accept this insurance
- Exclusions and waiting periods — whether certain treatments or conditions are excluded, or delayed by a waiting period
- Pre-approval requirements — which planned treatments need sign-off before you can get care
Going through these details is really what tells you what your insurance can actually deliver when you genuinely need it.
How to Choose the Right Health Insurance Coverage
The right policy comes down to your actual healthcare needs, your budget, and what’s genuinely available to you. Rather than deciding on premium alone, think through how you’ll actually use the insurance day to day.
- Start with your usual pattern of care. If you mostly see a doctor for the occasional checkup or minor illness, outpatient benefits probably matter most to you. If you’re more worried about the cost of a hospital stay or a major procedure, pay closer attention to inpatient coverage instead. Plenty of people genuinely need both, in roughly equal measure.
- Think about your ongoing medical costs. If you’re on regular medication, see a specialist, or need routine tests, go through the outpatient limits carefully. Small costs pile up fast when a policy only covers part of them.
- Review the limits and exclusions. A lower premium often means lower coverage limits, or certain services left out entirely — so compare the actual benefits side by side with the price, not just the headline number.
- Check the healthcare network. Confirm the hospitals, clinics, and pharmacies you’d actually use are included, and check whether the policy requires referrals or applies different rules outside its network.
- Understand what share of the cost falls on you. Even when something’s covered, you may still pay part of the bill — so look closely at copayments, deductibles, and any limits tied to individual services.
- Read the policy documents before deciding anything. If a benefit isn’t clear, ask the insurer directly what’s covered and what conditions apply. That one step alone can save you from a genuinely unpleasant surprise later.
Conclusion
Inpatient and outpatient health insurance cover two different kinds of care. Inpatient generally applies once you’re admitted to a hospital; outpatient covers the consultations, tests, and prescriptions that don’t require admission at all.
Both play a real role in managing healthcare costs. The right choice depends on your own situation, but understanding the limits, exclusions, and conditions attached to each matters just as much as comparing premiums.
Explore health insurance options through Tameen.om and compare the available benefits to find coverage that actually suits your needs and your budget.
What is the main difference between inpatient and outpatient health insurance?
Inpatient generally covers eligible expenses tied to a hospital admission. Outpatient covers services that don’t require admission — doctor consultations, diagnostic tests, and prescription medication among them.
Does health insurance usually cover both inpatient and outpatient care?
Many policies cover both, but the benefits vary quite a bit. Some plans offer fairly comprehensive coverage across both; others keep outpatient benefits limited or set very different caps for each type of care. Check the policy documents directly to confirm what’s actually included.
Can I use outpatient insurance for hospital treatment?
Outpatient coverage generally applies to treatment that doesn’t require admission. If you’re admitted, those costs would typically fall under inpatient benefits instead. That said, some hospital-provided services can still count as outpatient if no admission’s involved, so it’s worth checking with your insurer on how a specific treatment gets classified.
Explore All Insurance Options on Tameen
Discover a wide range of insurance plans and compare coverage to find the option that best fits your needs.
 Whatsapp